Biotech Funding from Private Rounds to IPO: Bicara, Zenas and MBX in 2024

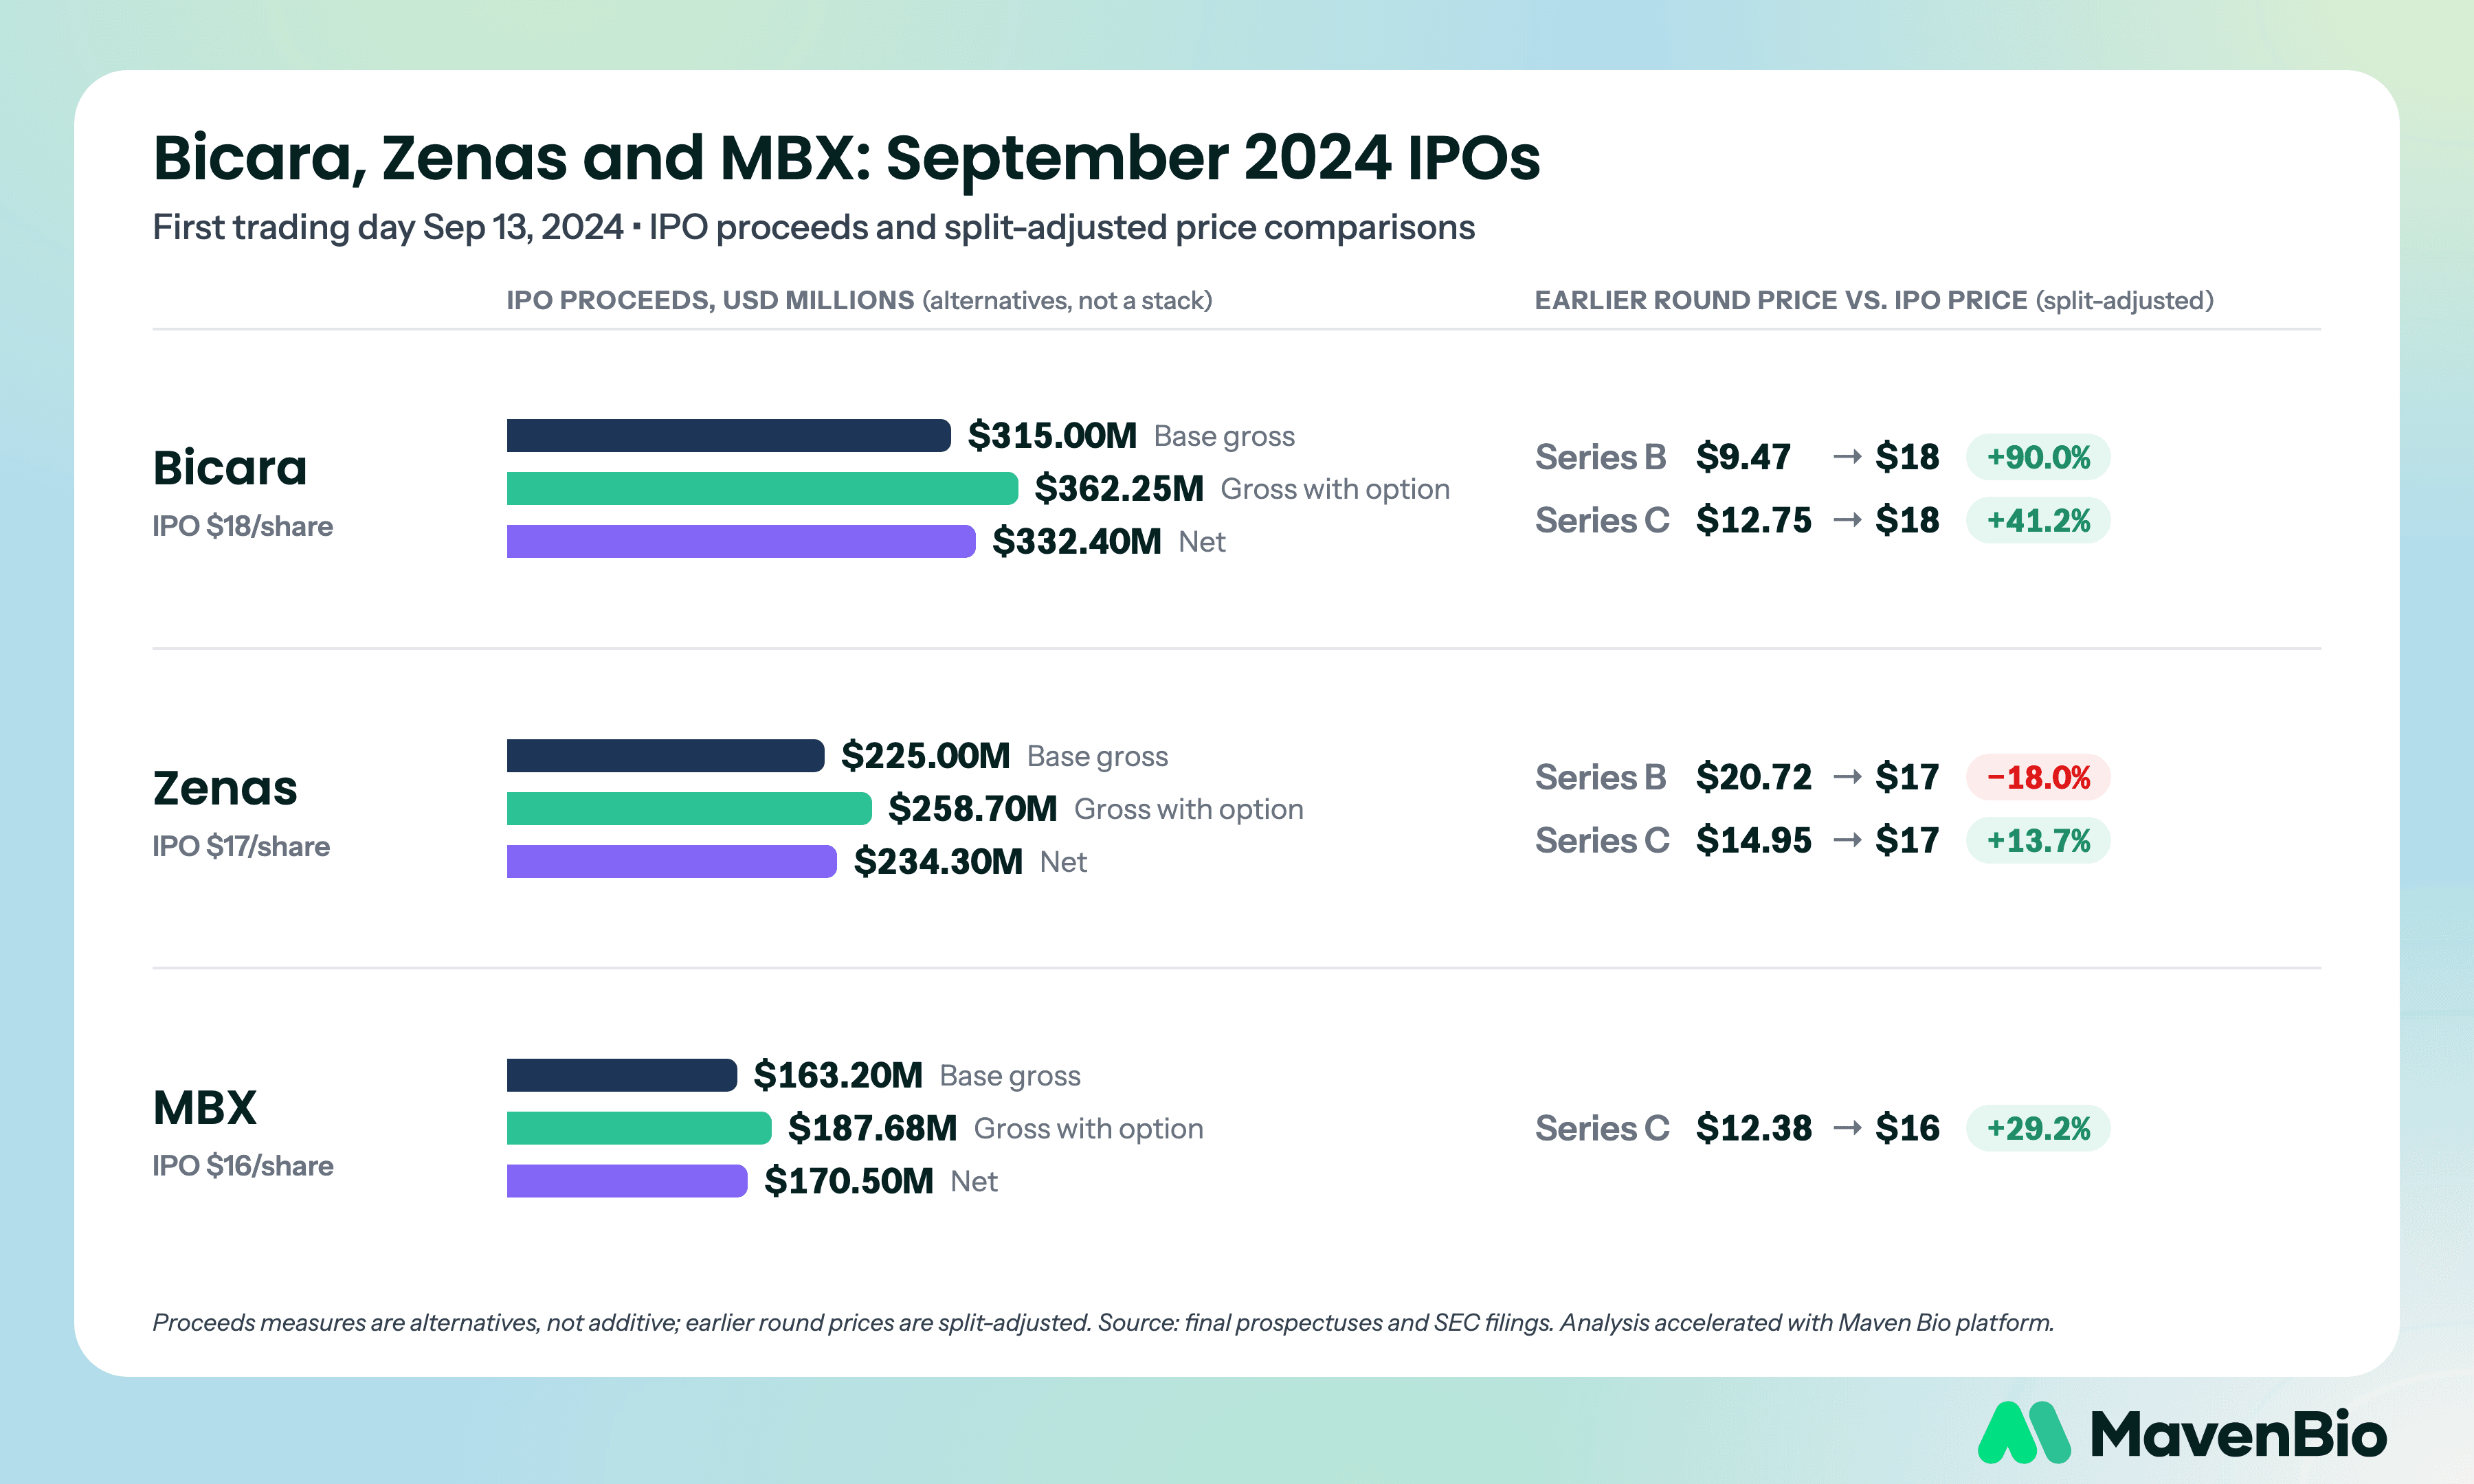
In September 2024, three biotechs, Bicara Therapeutics, Zenas BioPharma and MBX Biosciences, went public on the same day. Together they raised about $809 million including underwriter options, and their filings show how each company's IPO price compared with the prices paid in its earlier private rounds. Bicara Q3 filing; Zenas prospectus; MBX IPO announcement; Zenas annual filing; MBX annual filing
Bicara Therapeutics: Financing Cancer Development
Bicara's base offering was 17.5 million shares at $18, or $315.0 million gross. The additional 2.625 million option shares brought gross proceeds to $362.25 million. Its Q3 filing reported approximately $332.4 million net after underwriting and offering costs. The larger gross figure therefore cannot be attributed to 17.5 million shares alone. Bicara Q3 filing
Bicara's Series B closed in March, September and November 2023 at $1.025 per preferred share. Adjusting by 9.2435 gives approximately $9.47 per common share; the $18 IPO price was about 90.0% higher. December 2023 Series C pricing of $1.3796 converts to approximately $12.75, making the IPO premium about 41.2%. Bicara prospectus
At IPO, Bicara was developing ficerafusp alfa (BCA101), combining EGFR targeting with TGF-β trapping, in Phase 1/1b solid-tumor studies. Its planned Phase 2/3 study paired the agent with pembrolizumab for first-line recurrent/metastatic head-and-neck squamous-cell carcinoma, excluding HPV-positive oropharyngeal cancer. That was a development plan, not an approval. Bicara prospectus
Zenas BioPharma: Different Outcomes by Financing Round
Zenas priced 13,235,294 base shares at $17, approximately $225.0 million gross. The exercised option increased the total to 15,220,588 shares and $258.7 million gross; reported net proceeds were $234.3 million. The IPO closed September 16, 2024, rather than on its first trading day. Zenas prospectus; Zenas annual filing
Zenas's November 2022 Series B price was $2.38666 per preferred share, equivalent to about $20.72 per common share after the 8.6831-for-one conversion adjustment. The May 2024 Series C price of $1.72131 becomes approximately $14.95. Its $17 IPO price was therefore about 18.0% below Series B but 13.7% above Series C. These are price comparisons, not measures of realized investor returns. Zenas prospectus
At IPO, Zenas's obexelimab program included Phase 3 IgG4-related disease, Phase 2 multiple sclerosis and lupus, and the Phase 2 portion of a Phase 2/3 warm autoimmune hemolytic anemia trial. Viridian and Dianthus arrangements concerned specified Greater China rights, not worldwide ownership of those partners' assets. Zenas prospectus
MBX Biosciences: Funding Endocrine and Metabolic Programs
MBX's base offering comprised 10.2 million shares at $16, or $163.2 million gross. With the option, it sold 11.73 million shares for $187.68 million gross, closing September 16, 2024. Its annual filing reported $170.5 million net after fees and costs. MBX IPO announcement; MBX annual filing
Its August 2024 Series C preferred price of $1.03 becomes approximately $12.38 on the 12.0221-for-one adjusted common-share basis. The $16 IPO price was about 29.2% higher. MBX 2109, later named canvuparatide, had entered Phase 2 hypoparathyroidism testing in August 2024; MBX 1416 targeted post-bariatric hypoglycemia. These were investigational programs, not commercial products at IPO. MBX annual filing
What the Three Offerings Show—and What They Do Not
A comparable financing analysis starts with the same basis for each company: gross base proceeds, gross proceeds including exercised options, or net proceeds after fees. The $808.7 million combined figure above uses gross proceeds including options for all three. An IPO raises capital for the issuer; it does not automatically mean existing investors sold their holdings or realized a profit. Bicara Q3 filing; Zenas annual filing; MBX annual filing
The price comparisons adjust private preferred-share prices onto the common-share basis used at IPO. Company equity valuation also depends on the applicable share count, including dilution; investor outcomes depend on conversion terms, rights, purchase timing and any eventual sale. A near-doubling of the offer price versus an earlier adjusted purchase price is not proof that the company's valuation doubled. Bicara prospectus; Zenas prospectus; MBX annual filing
These three offerings show that clinical-stage companies in oncology, immunology and endocrine disease could raise public capital in September 2024. They do not, by themselves, establish a sector-wide resurgence or prove that later-stage assets consistently delivered better investor returns. For financing comparisons, retain the dates, clinical milestones and capital structure behind each number rather than ranking companies by the size of their IPO.